Guides
October 22, 20268 min read
Healthcare Loans for Addiction Treatment: Pros and Cons
Use this decision process to compare treatment loans, verify insurance, review repayment terms, and limit unnecessary family debt.
NT
Northbound TreatmentNorthbound Treatment
Editorial Team
Compare treatment financing offers by checking total repayment, APR, fees, insurance adjustments, payment timing, and exit terms.
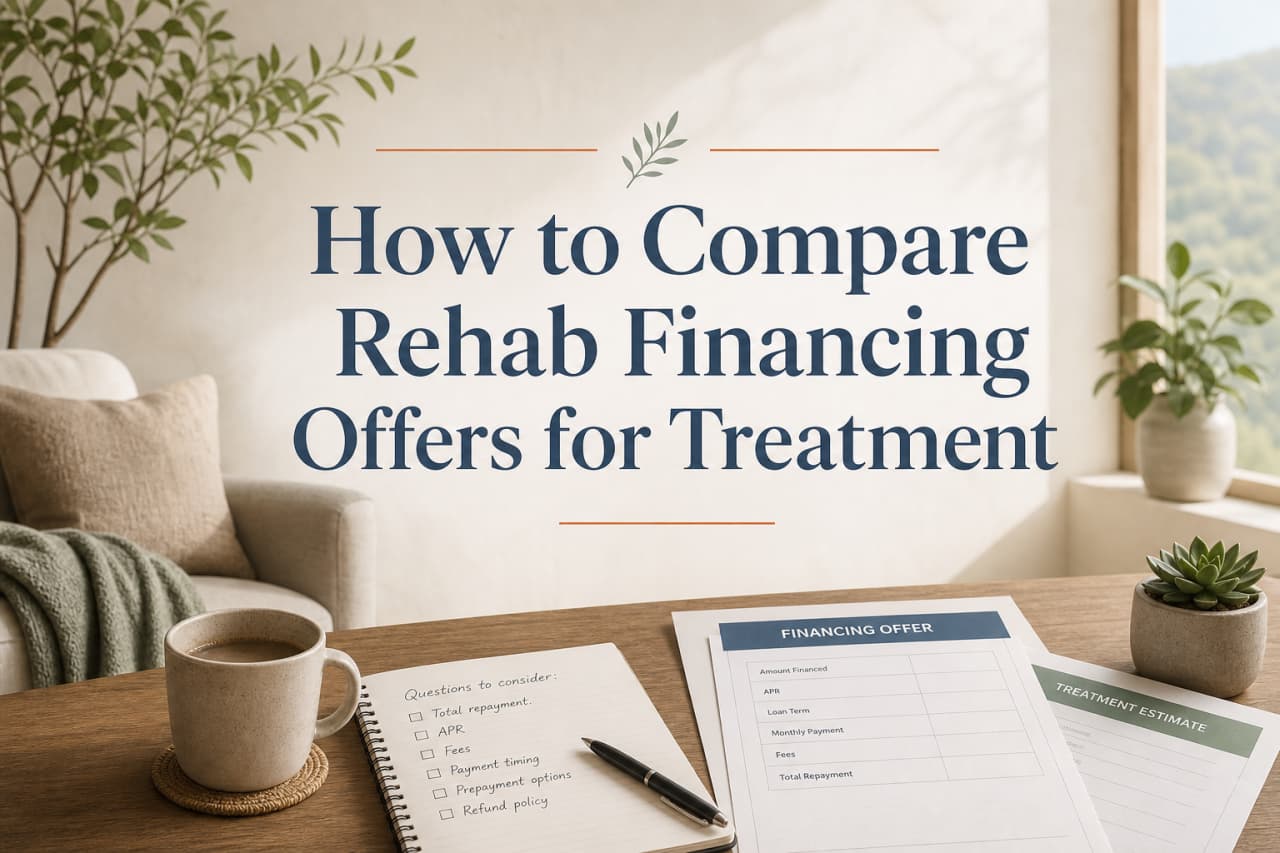
To compare rehab financing offers, line up APR, fees, total repayment, payment timing, prepayment rules, and refund handling against one written treatment estimate. A longer loan term can raise total interest even when the monthly bill looks easier to carry, and that gap only shows up once the offers sit side by side.
Financing can open a path into care when insurance leaves a balance. It can also leave debt that outlasts treatment. Compare contracts on equal terms, and don't let a lender's approval amount decide how much your family borrows.
Start with a written disclosure from each lender. Record the amount financed, annual percentage rate, loan term, monthly payment, fees, and total repayment. Finish insurance verification with Northbound before you treat any financing figure as final.
APR deserves close attention. The interest rate covers the cost of borrowing the principal, while APR can fold in interest plus certain loan fees. The Consumer Financial Protection Bureau's APR explanation shows why APR usually gives the clearer side-by-side read.
| Term to compare | What to record | Why it matters |
|---|---|---|
| Amount financed | The exact principal shown in the contract | This is the amount on which borrowing costs are based. |
| APR | The disclosed annual percentage rate | APR helps compare offers with different rates and fees. |
| Loan term | The number of months or payment periods | A longer term can lower the payment while raising total interest. |
| Monthly payment | The required amount and first due date | The payment must fit alongside housing, food, transportation, and medical costs. |
| Fees | Origination, processing, late, returned-payment, or other listed charges | Fees can change the real cost or reduce the funds delivered for treatment. |
| Total repayment | The full scheduled amount if paid as agreed | This is often the most useful bottom-line figure. |
| Prepayment terms | Any penalty, fee, or interest rule tied to early payoff | Your family may want to pay the balance down after an insurance payment or other funds arrive. |
| Refund process | Where unused or returned treatment funds go | Refunds may need to be applied to the loan rather than sent directly to the borrower. |
Once the monthly payment fits your budget, give total repayment more weight than the payment alone. A low payment stretched across a longer term can cost more overall. Ask each lender to state the total in writing, and skip the mental math from a verbal quote.
“Price the whole agreement.”
Borrow against the expected uncovered balance, not the maximum a lender will approve. Begin with insurance verification and request a written treatment estimate tied to the recommended level of care. Subtract confirmed insurance payments, deposits, and cash your family can put in without missing rent, food, or other basics.
Northbound Treatment in Garden Grove, California, holds DHCS license 300661CP and accepts plans from Aetna, Anthem, BlueCross BlueShield, Cigna, Compsych, First Health Network, GEHA, Health Net, ILWU, Magellan, MHN Insurance, NYSHIP, Premera Blue Cross, TriCare, and USAMCO. Coverage still depends on the plan, medical necessity, authorizations, deductibles, and other policy terms. Self-pay and financing options can be discussed when coverage is limited.
Ask Northbound to verify benefits and explain the result in plain language. Request the estimated family responsibility for the proposed level of care, and confirm which services need authorization or continued clinical review. Ask how later insurance payments, denials, or adjustments will change your balance, then treat the remaining estimate as your borrowing ceiling.
A treatment estimate and a financing approval answer different questions. The estimate speaks to expected care costs, while the approval states how much a lender may extend under its credit rules. Borrowing the full approved amount can leave your family paying interest on money that was never needed.
The Substance Abuse and Mental Health Services Administration's payment resource lists ways families can review insurance, public programs, and other payment resources. Availability depends on location and eligibility.
Ask for the treatment estimate, insurance verification, and financing disclosure as separate documents. Keeping them separate makes later adjustments easier to track.
Rate type, fee structure, and payoff rules can shift what your family ultimately pays. Ask whether the rate is fixed for the full term or can move. If it can move, request the adjustment schedule, any rate cap, and a written example of how the required payment could change.
Confirm how origination and processing fees are handled. A lender may add a fee to the balance or deduct it from the amount sent for treatment, and either method can widen the gap between the approved loan and the money available for care.
Ask how interest accrues and how extra payments are applied. An early payment should be credited under the written agreement. Read the prepayment section for penalties or other limits, especially if your family expects a later insurance payment, a tax refund, or help from a relative.
A co-signer accepts legal responsibility for the debt if the primary borrower doesn't pay. Before anyone signs, each borrower should receive the full contract and know when payments begin, how missed payments are reported, and whether the lender offers a documented hardship process.
Loan applications can trigger credit checks, so ask whether an initial rate check uses a soft inquiry and when a hard inquiry occurs. The CFPB publishes plain-language information about credit reports and scores so families can review their records before applying. Northbound's admissions line is (866) 311-0003 if you have treatment-cost questions while you read lender paperwork.
“Get every promise in writing.”
Ask how the financing agreement handles a revised treatment plan, an early transition, or a later insurance payment. Northbound provides Drug and Alcohol Detox, Residential Treatment, Partial Hospitalization, Intensive Outpatient, Sober Living, Online Treatment, and Aftercare. Clinical need shapes which level is recommended and how long care continues.
Many clients complete a 30, 60, or 90 day program across the continuum, but duration follows clinical need and ASAM criteria. A financing contract should explain what happens when the final balance differs from the original estimate. The loan term shouldn't drive clinical decisions.
Clarify where the lender sends funds, to the treatment provider or the borrower. Confirm who receives a refund if the final treatment charge is lower, and whether that refund reduces loan principal automatically. Ask how long a balance adjustment takes, whether interest keeps accruing while an insurance claim is pending, and which documents are needed to change or cancel a disbursement.
Keep copies of the original estimate, benefit verification, authorization notices, lender disclosure, payment receipts, and account adjustments. Note the name and date of every phone conversation. If a verbal answer affects cost, ask the company to confirm it by email or through its secure portal.
Pause if a company won't provide the APR, total repayment, fee list, lender identity, or cancellation terms before signing. Blank contract fields and unexplained charges are also reasons to stop. Don't sign a document that differs from the offer you already reviewed.
High-pressure deadlines deserve scrutiny. Treatment can be time-sensitive, yet your family still needs the written financing terms. You can raise treatment and insurance questions directly with admissions at the number above instead of relying on a lender to explain clinical care.
Be wary of claims that approval is guaranteed or that fees don't matter because the monthly payment is low. Ask which company funds the loan, who collects payments, where complaints go, and what state law governs the agreement. The CFPB's personal loan resources outline common loan structures and borrower risks.
The treatment provider and the lender hold different responsibilities. Confirm care costs and insurance with Northbound, and confirm borrowing terms, fees, and repayment duties with the lender. If the contract is unclear or ties the debt to property as collateral, consider having a qualified financial or legal professional review it.
If a lender pressures you to sign before providing complete written terms, stop the application and request the disclosure.
Choose the lowest total-cost offer that carries a fixed, manageable payment and clear adjustment terms. A cheaper loan becomes a poor fit if its due date collides with income, its payment puts rent or food at risk, or its refund rules leave your family paying interest on returned treatment funds.
Verify insurance and obtain one written treatment estimate. Enter every offer into the same comparison table without changing assumptions, and drop offers with unclear rates, missing disclosures, or payments that threaten basic expenses. Compare total repayment and early-payoff terms among what's left, then read the final contract against the original disclosure before anyone signs.
If two offers have similar payments, prefer the one with lower total repayment, fewer fees, and no penalty for early payoff. If one offer has the lower total but a payment your family can't reliably make, reject it. A missed payment can create late fees and credit damage that erase the initial savings.
Ask about self-pay arrangements and financial assistance before taking on debt. Northbound can review insurance benefits, discuss payment information, and explain which treatment levels may be covered. That conversation won't guarantee approval or coverage, but it can cut down guesswork before your family applies. Have written offers ready when you call (866) 311-0003.
“Borrow after verification, not before.”
Compare APR first because it can reflect both interest and certain fees. Then check the interest rate, total repayment, fee list, and payoff rules. APR alone won't tell you how refunds or early payments are handled.
No. A lower payment may come from a longer repayment term, which can increase total interest. Use the total repayment figure to compare cost, then confirm that the required payment fits your monthly budget.
Verify benefits first whenever time and medical safety allow. Northbound can explain known coverage terms before your family sets a borrowing amount.
Ask about eligibility requirements before submitting a full application. A co-signer may improve access to some offers, but that person becomes responsible for repayment under the contract. Compare self-pay and financial assistance arrangements before adding a co-signer.
No. Benefit verification explains available plan information. Final payment can still depend on medical necessity, authorization, claim processing, and policy rules. Ask how any later insurance adjustment will be credited to your treatment balance and loan.
Bring the insurance card, policyholder information, treatment estimate, available lender disclosures, and a short list of payment questions.
This article provides general educational information and isn't a substitute for medical, legal, or financial advice. If withdrawal may be dangerous, seek medical care rather than waiting for financing paperwork. If you're in a crisis, please call 988 or 911.
For a confidential conversation about insurance verification, treatment levels, and payment arrangements at Northbound Treatment, call (866) 311-0003. Keep your insurance card and any written financing offers nearby so the admissions team can answer the right questions.
About the Author
Helpful educational resources from Northbound Treatment.
In This Article
Tags
Use this decision process to compare treatment loans, verify insurance, review repayment terms, and limit unnecessary family debt.
See what should transfer between detox and residential care and what families need to confirm before admission.
Families facing treatment now must weigh self-pay costs against the medical risk of waiting for a new insurance plan.
Take the Next Step
Our admissions team is available 24/7 — confidential, no-obligation, and judgment-free. Let us help you or your loved one find the right path forward with medical detox, residential treatment, or outpatient care in Orange County.