Guides
October 15, 202610 min read
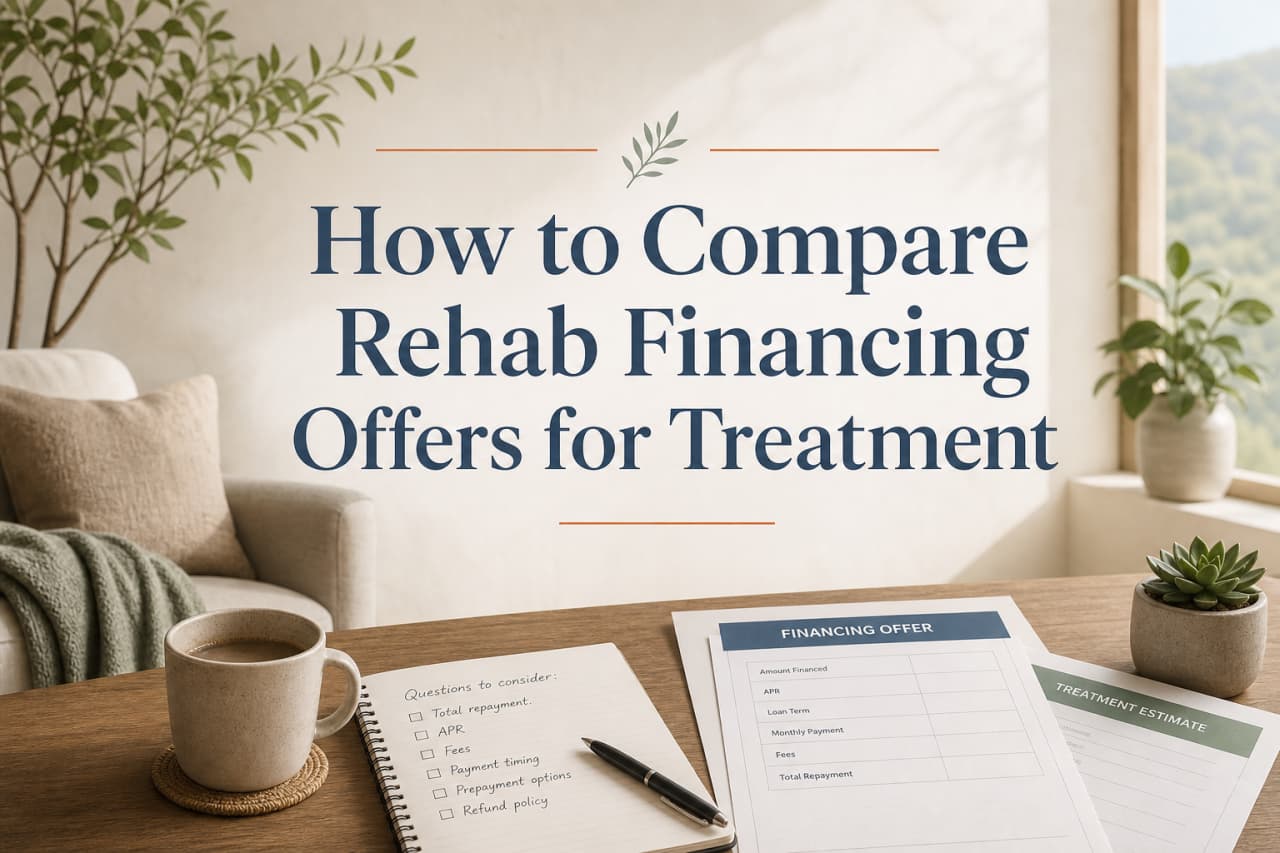
How to Compare Rehab Financing Offers for Treatment
Compare treatment financing offers by checking total repayment, APR, fees, insurance adjustments, payment timing, and exit terms.
NT
Northbound TreatmentNorthbound Treatment
Editorial Team
Use this decision process to compare treatment loans, verify insurance, review repayment terms, and limit unnecessary family debt.
Healthcare loans for addiction treatment pros and cons come down to access now against interest, fees, and repayment risk later, on a bill that insurance may shrink or erase. Northbound usually finishes a benefits check within about one business hour, and the result often changes how much a family needs to borrow.
Verify your benefits and the recommended level of care before you apply anywhere. Fast approval doesn't help when the amount you request rests on incomplete insurance information or an estimate that can shift after assessment.
If you are in a crisis, please call 988 or 911. This article provides general education and doesn't replace professional medical, legal, or financial advice.
Most products give you borrowed money for an eligible healthcare expense, then collect it back on a schedule. Depending on the lender, that could be an unsecured installment loan, a revolving credit account, or financing offered through a third party connected with a provider.
Terms differ between lenders. One loan may have a fixed rate and payment, while another charges variable interest or deferred interest under certain conditions. The Consumer Financial Protection Bureau's personal loan resources explain common loan terms and consumer protections.
Financing and clinical admission are separate decisions. Northbound Treatment Services starts with a free, confidential pre-admission assessment, and the team then verifies available insurance benefits, so your family can borrow with better information.
Start with total cost and repayment risk rather than the advertised monthly payment. A longer term can lower the payment while raising the amount you pay over time, so read every fee line before you sign.
| Decision factor | Possible advantage | Risk or tradeoff |
|---|---|---|
| Treatment timing | Funds may cover a verified gap without waiting to save the full amount. | Loan approval doesn't guarantee clinical admission or insurance payment. |
| Payment structure | A fixed installment loan can provide a set payment schedule. | Interest and fees raise the total cost of care. |
| Emergency savings | Borrowing may let a family retain some cash for housing, food, or travel. | Monthly debt can reduce money available for aftercare and household needs. |
| Cosigner | A lender may consider a cosigner during underwriting. | The cosigner becomes legally responsible for the debt. |
| Coverage gaps | A loan may bridge an amount left after verified benefits. | The family may borrow too much if benefits haven't been confirmed. |
| Speed | Some lenders make decisions quickly. | Pressure to sign can prevent a careful review of fees and cancellation terms. |
Insurance comes first because it can change the size of the gap. Northbound is an in-network preferred provider with 15 or more major plans, including Aetna, Anthem, BlueCross BlueShield, Cigna, and TriCare. Coverage still depends on your specific policy, network rules, medical necessity, and authorization requirements.
HealthCare.gov's explanation of mental health and substance use coverage is a useful starting point, but your plan documents and benefit verification control the actual answer.
Finish the clinical assessment and benefit verification before you compare loan offers. Once you have the results, give every lender the same facts so the offers reflect one expected treatment plan. Detox usually runs 5 to 10 days and residential care 30 to 90 days, so the care level alone can change the estimate several times over.
Keep copies of benefit summaries, estimates, lender disclosures, payment receipts, and written communications. If you discuss terms by phone, write down the date, the person's name, and the answer, because memory won't hold up for a decision that can affect the family budget for years.
A loan can fit once your family has confirmed the clinical need, verified insurance, reduced the borrowing amount, and found a payment that leaves room for basic expenses and continuing care.
The strongest use case is a known funding gap attached to a defined care plan. Northbound offers medical detox, residential treatment, partial hospitalization, intensive outpatient care, sober living, online treatment, and aftercare, with detox and residential care at The Grove in Garden Grove. Assessment and ASAM criteria decide where a person enters, so a 5 to 10 day detox stay produces a very different estimate than a 30 to 90 day residential stay.
Borrowing may also make sense when waiting would create a meaningful clinical risk and the responsible borrower has read the full agreement. Urgency doesn't excuse unclear terms, so ask the lender how funds are released, how cancellations work, and where any approved refund would go.
Use extra caution with a cosigner. The Federal Trade Commission's guidance for cosigners explains that a cosigner takes legal responsibility for repayment if the primary borrower doesn't pay.
“Borrow for an assessed treatment need, not for the largest amount a lender approves.”
Pause borrowing when the treatment amount is uncertain, benefits haven't been checked, or the payment would put housing, food, or ongoing healthcare at risk. Approval is a lender's credit decision and says nothing about clinical fit. Northbound can't accept Medicare or Medicaid at this time, so families relying on either program need to know that before they discuss private borrowing.
Walk away from any pressure to sign before you've reviewed the annual percentage rate and total repayment. The same goes for a lender that won't explain deferred interest, origination charges, late fees, cancellation rules, or the provider's refund process.
Don't assume insurance will repay your loan later, since claims can depend on authorization, medical necessity, network rules, and plan exclusions. For example, a family that borrows $20,000 expecting a full reimbursement can end up carrying the whole balance if authorization is denied.
Financial pressure can also push families toward unsafe shortcuts. Alcohol and benzodiazepine withdrawal can become life-threatening, and Northbound's licensed detox program at The Grove provides medical monitoring around the clock when detox is clinically indicated. Debt shouldn't decide whether someone gets medically supervised detox.
The assessed level of care should set the financial estimate, and each step carries a different time commitment. Northbound's continuum moves through medical detox, residential care, PHP, IOP, and aftercare as clinical needs change. Many clients complete a 30, 60, or 90 day program overall.
PHP can provide up to six hours of programming per day, five to six days each week, while IOP requires at least nine service hours per week. Those are budgeting figures, and the care team sets the actual length after meeting your loved one.
The ASAM Criteria guide placement and transitions according to clinical need, so ask which phases your plan may cover and which part, if any, your family would finance.
Avoid borrowing for every possible phase at once unless you receive a clear reason. A step-down plan can change with clinical progress, insurance authorization, living conditions, and the need for ongoing support, so finance only the phase that's defined.
Ask admissions for the clinical and insurance facts that affect the amount. Northbound's admissions line is open 24 hours a day, and the initial conversation is free, confidential, and carries no obligation.
Take notes and ask for plain-language explanations. Before accepting private debt, read Northbound's information about financial assistance and payment options. That page covers available support without replacing a lender's disclosures or your own financial review.
It may, if the lender permits the expense and the treatment provider accepts that payment arrangement. Confirm eligibility, disbursement, cancellation, and refund terms before signing. Northbound provides both medical detox and residential treatment at The Grove.
Verify benefits as early as clinical urgency allows. Northbound can typically complete verification within about one business hour, though an insurer's response isn't a guarantee that every claim will be paid.
No. A longer repayment term can lower the monthly bill while increasing total interest. Compare the annual percentage rate, fees, term, and total of payments.
A lender may allow a qualified parent or relative to cosign. The cosigner accepts legal responsibility for the debt, so both parties should receive and review the full agreement.
Ask for the verified responsibility, the reason for any limitation, and the appeal or authorization process that may apply. Then compare financial assistance, self-pay, and financing options before choosing a loan.
No. Loan approval addresses financing, while admission and placement follow Northbound's clinical assessment, medical review, and program criteria.
Call Northbound Treatment Services at (866) 311-0003 for a confidential pre-admission assessment and insurance verification. You can also send our admissions team a confidential message. Our licensed facility is located at 9842 13th St, Garden Grove, CA 92844, under California DHCS License #300661CP.
About the Author
Helpful educational resources from Northbound Treatment.
In This Article
Tags
Compare treatment financing offers by checking total repayment, APR, fees, insurance adjustments, payment timing, and exit terms.
Payment plans split an estimated rehab balance over time. Compare deposits, fees, insurance adjustments, and financing risks before signing.
You'll see how to set a realistic goal, write a campaign page, and protect your loved one's privacy, so you can decide whether crowdfunding fits your family's plan.
Take the Next Step
Our admissions team is available 24/7 — confidential, no-obligation, and judgment-free. Let us help you or your loved one find the right path forward with medical detox, residential treatment, or outpatient care in Orange County.